Thursday, October 8, 2026

Your Employment Bond Has a Proof Problem

The clause usually sits a few pages into the offer letter, under a heading like Service Agreement: leave before a fixed term ends and you pay a stated sum as liquidated damages for training. Freshers at Indian IT services firms sign it on joining day. That employment bond is enforceable more often than office WhatsApp groups claim, but the printed number is where your employer's case starts, not where it ends.
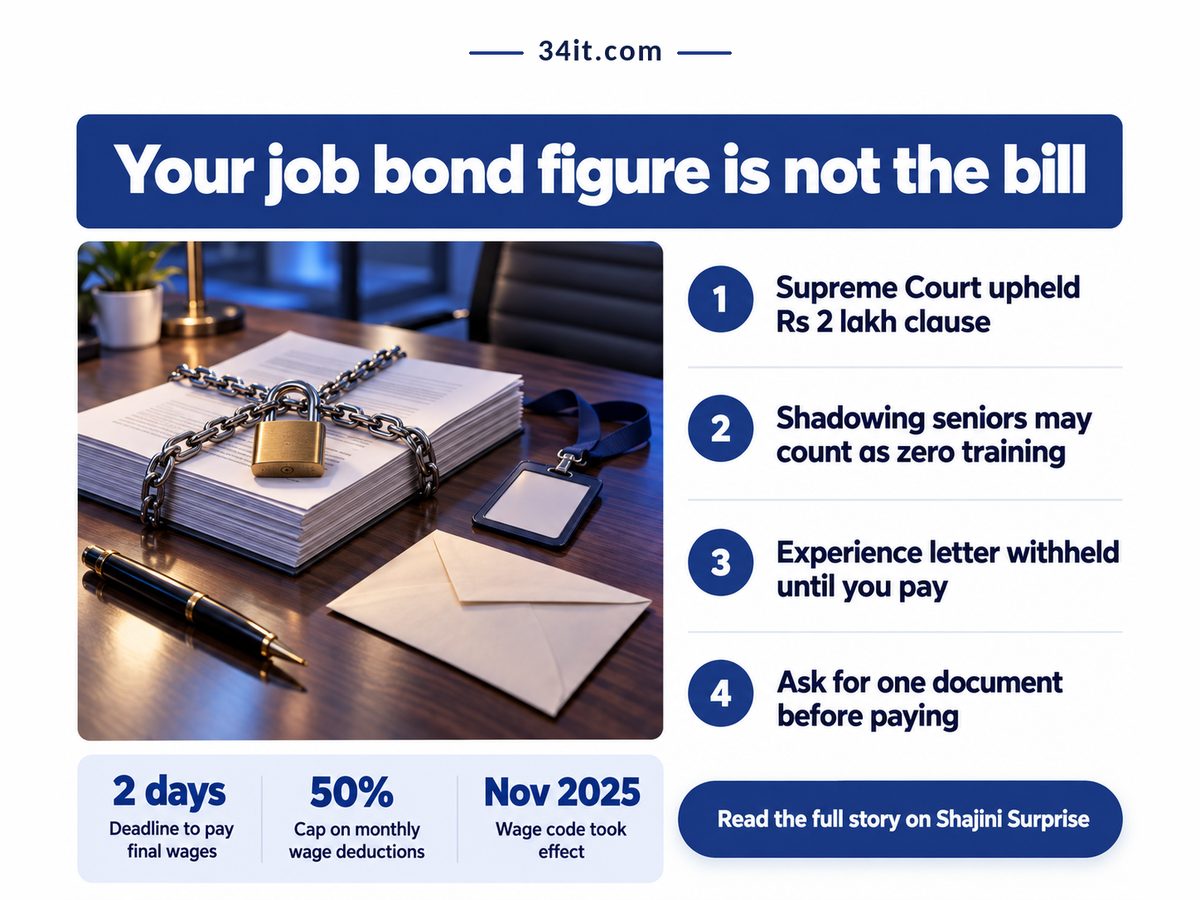
Padlocked employment bond contract on a desk beside four points on recovery limits

A bond can be enforced, but only for training cost your employer can prove, reduced for the time you served, and never by cutting it from your final salary.

  • The Supreme Court upheld a bank's bond clause in May 2025, so calling every bond void no longer works.
  • The stated sum is a ceiling; courts cut damages for months served and thin training.
  • Training recovery is not a permitted wage deduction, so it cannot come out of your full and final settlement.
  • Before paying anything, ask HR in writing for the itemised training-cost record.

Is an employment bond legal in India now?

Yes, a bond that ties you to a minimum service period is generally enforceable in India after the Supreme Court's 2025 ruling, but only for loss the employer can show and in proportion to your pay.

The case is Vijaya Bank v Prashant B. Narnaware, decided by the Supreme Court on 14 May 2025. An officer agreed to serve three years or pay ₹2 lakh, then left early. The Court held that a covenant operating during employment is not a restraint of trade under section 27 of the Contract Act. Quoting section 27 at HR no longer ends the conversation; the fight is now over amount and proof.

The win is narrower than it looks. According to Bharucha & Partners' note on where bonds stand now, the sum was held non-penal because the bank bore real recruitment cost and the officer was a senior middle manager who could pay. My reading is that the ruling quietly helps freshers, since proportionality to pay is now part of the test.

It also binds less than it seems. Vijaya Bank is a public sector bank, so for a private IT firm the judgment is persuasive, not binding, as one May 2025 post-ruling analysis notes. Tenure also moves your gratuity under the 2026 rules too. If the company is easing you out, through silent layoff signals tech workers miss, keep every email: in my view that weakens its claim to damages.

Four numbers decide what you hand over. Two come from the Code on Wages, 2019, in force since 21 November 2025. Two earlier rulings Bharucha cites, Ledalla Ravichandar v Satyam and Sicpa India v Manas Pratim Deb, cut damages for time served and pay scale. Saurabh Seth, in Bar & Bench on 24 January 2026, valued on-the-job training; that is practitioner opinion, not a ruling.

Deadline for Final Wages

2 working days

Pay cannot wait on disputes

Recoverable Cost of Shadowing

₹0

If KT was your training

Rulings Cutting Bond Damages

2

Time served lowers the bill

Cap on Deductions per Wage Period

50%

Half your pay stays protected

Take the deadline: under section 17(2), HR cannot park your last salary during a bond dispute. Section 18 lists every permitted deduction, from fines and advances to tax and court orders, and training recovery is not on it. The lawful route is a civil suit.

"

A bond is a claim your employer has to prove in court, not a line it gets to subtract from your last payslip.

So what does a court actually allow when you leave early?

What happens if you break a training bond?

If you leave before the bond period ends, your employer can claim damages, but courts tend to cut the stated sum to proven training cost, reduce it for months served, and the claim has to go through a suit.

In the middle column, the first line is the bond and the second is what courts and the Code have allowed.

Dimension Bond vs court What it means for you
๐Ÿ’ฐ Amount owed Bond full sum, any exit date
Court proven loss, s.74 ceiling
✅ The printed figure is a maximum, not a bill
⏱ Time served Bond same sum at any month
Court month 30 of 36, a sixth left
✅ Each month you stay shrinks the claim
๐Ÿ›  Training proof Bond training left undefined
Court invoices, dates, trainers
⚠️ Thin paperwork weakens their case
๐Ÿ“Š Pay scale Bond one sum for every grade
Court 2025 test weighs your pay
⚠️ Freshers hold the stronger fairness case
๐Ÿงพ Final pay Bond netted from your F&F
Court s.18 list has no bond line
✅ Your last salary arrives untouched
⚖️ Exit papers Bond letter held till paid
Court no lien on documents
✅ Refuse the swap and keep it in email
๐Ÿ”’ Notice gap Bond rolled into the bond sum
Court unserved days' pay only
❌ You still owe this, as a separate sum
๐Ÿ Best suited for Pay classroom spend proven
Contest training was only shadowing
๐Ÿ Ask for the record before deciding

Five of eight rows favour you or turn on paperwork the employer controls. Classroom training with invoices is a real claim; shadowing mostly is not.

Served: 24 months. Unserved: 12 months. Two thirds of the term. One third. ₹1,33,333 no longer at stake. ₹66,667 maximum at stake.

Leaving at month 24 of a three-year, ₹2 lakh bond puts at most about ₹66,667 at risk, less if receipts are thin. That is our own pro-rata arithmetic on the Vijaya Bank terms, not a court's figure.

Can HR hold back your experience letter or final pay?

No, withholding your experience letter until you pay the bond is pressure rather than a legal remedy, and your final wages fall due on time whatever the bond dispute, so put every demand in writing.

Seth calls trading a bond payment for an experience letter illegal leverage. It still works more often than it should (a missing letter stalls the next background check). Specific performance of a service contract is barred, so the most a bond becomes is a money claim.

Notice is separate. Skip part of it and, on Seth's reading, you owe at most salary for the unserved days, never bundled into the bond figure. Check the payment date against the 48-hour full and final settlement deadline, and watch for:

  • A bond letter with one lump sum and no cost breakdown.
  • A training recovery line on the F&F statement, a separate issue from the wage-definition rule that reshaped take-home pay.
  • Notice pay and bond damages merged into one figure you are asked to sign.

Key Takeaways to act on: check these before you pay

  • Your offer letter names a training cost, not only a penalty.
  • HR can show invoices or trainer records for your batch.
  • Your training was a formal programme, not shadowing.
  • Less than a sixth of the bond term is left to run.

Two or more false: contest rather than pay.

The decision is whether to pay or contest, and it turns on one document. This week, email HR for the itemised training-cost record behind your bond and state that you expect your final wages in full. If the record exists, offer your unserved share of the proven cost. If it doesn't, decline and let the company decide whether a suit is worth it.
Monday, October 5, 2026

50% Wage Rule: When Take-Home Pay Drops

Section 2(y) of the Code on Wages, 2019 defines wages as basic pay, dearness allowance and retaining allowance. HRA, conveyance and the rest of the payslip sit outside that definition, but only up to a point: once those exclusions pass half of total remuneration, the excess is added back and treated as wages. That add-back is the 50% wage rule. The Code commenced on 21 November 2025 and its central rules were notified on 8 May 2026, according to a 13 August 2026 analysis by law firm KS&K, so a salary restructure in this year's revision letter is compliance, not a favour.

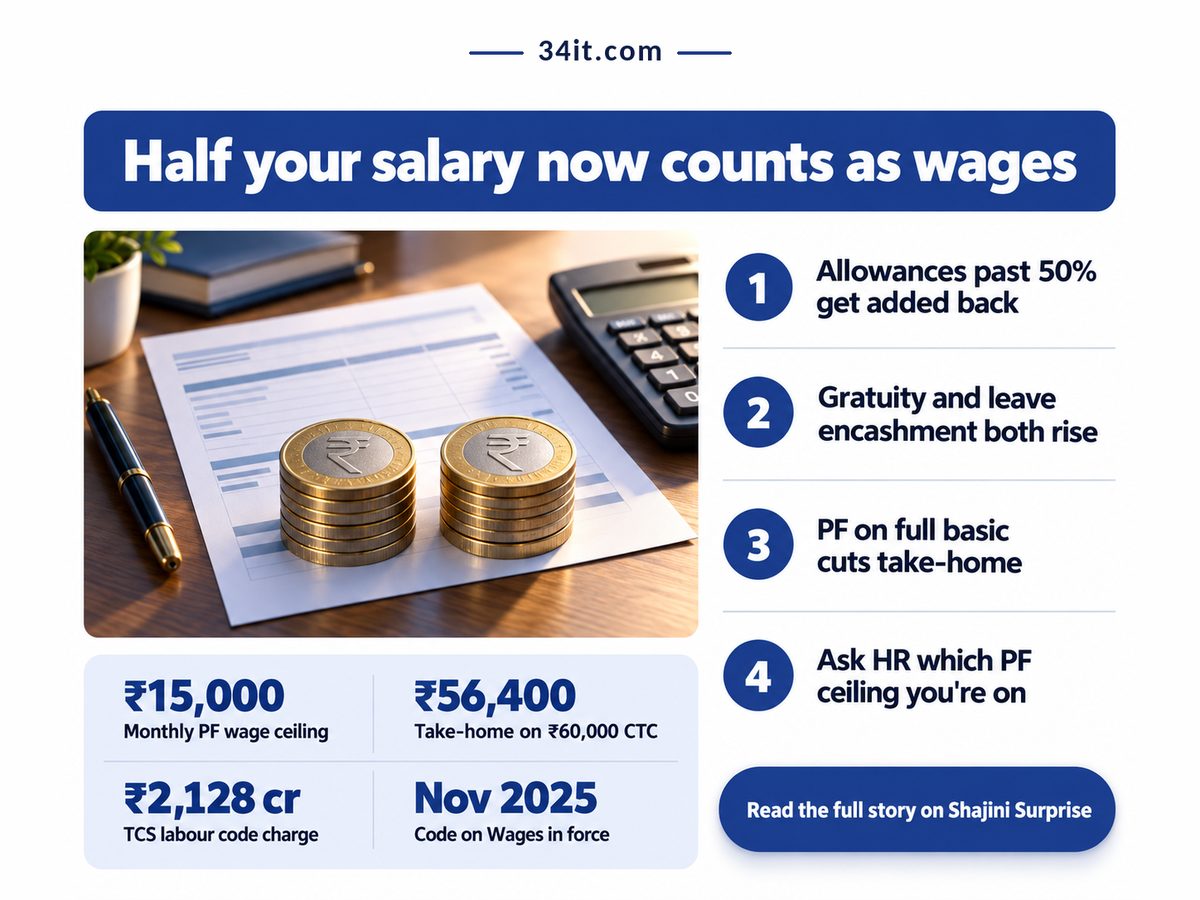
50% wage rule infographic: salary slip, split rupee coins and PF ceiling stats

Take-home falls only if provident fund is calculated on full wages instead of the statutory ceiling; gratuity and leave encashment rise either way.

  • Allowances above half of total pay are deemed wages, even if the payslip never relabels them.
  • PF deducted on the ceiling leaves take-home unchanged, and anything above it is voluntary.
  • On a ₹60,000 monthly CTC, PF on full wages takes ₹3,600 more out of your hand each month.

How the 50% wage rule counts your pay

The rule adds up everything Section 2(y) excludes from wages, compares that total with half of your total remuneration, and counts any excess back as wages, the base on which gratuity and leave encashment are computed.

The exclusions are listed. KS&K's reading of the Code names HRA, conveyance, employer contributions to PF and pension, gratuity, performance incentives and overtime. Add those lines on your payslip and divide by total pay. Under half, nothing moves. Over half, the gap crosses into wages. For contract staff the same base now feeds pro-rata gratuity after one year of fixed-term service.

Employers ran this arithmetic months ago. A 21 January 2026 tally by CA Rajput of Q3 FY26 company disclosures lists one-time labour-code charges at the largest Indian IT services firms, booked because a bigger wage base means a bigger gratuity and leave-encashment liability on service already worked. I think the payslip is the wrong end of the story: the larger change sits in what you are owed when you leave, and the four figures below decide whether you should expect it.

Time the Code Has Applied

10 months

Your next revision is in scope

TCS One-Time Charge

₹2,128 crore

Higher gratuity already funded

IT Majors Booking a Charge

6 firms

Your employer likely did too

Exclusions Allowed Before Add-Back

50% of pay

Beyond it, allowances become wages

A provision is money set aside for gratuity and leave encashment the company now accepts it owes on years you have already worked. If your employer booked one, the higher payout is sitting in its accounts. Check your exit payout for it before you sign a full and final settlement under the 48-hour deadline.

"

Six of India's largest IT employers have already paid for your higher gratuity. Whether your exit cheque shows it is the only question left.

Will take-home salary reduce under the new labour codes?

Take-home falls only if your provident fund is calculated on the full wage figure; the Labour Ministry said on 10 December 2025 that PF deducted on the ₹15,000 ceiling leaves take-home unchanged.

The Ministry went further: contribution above the ceiling is voluntary. OutlookMoney's 13 December 2025 report on that clarification works one salary through, a ₹60,000 monthly CTC made up of ₹20,000 in wages and ₹40,000 in allowances. Allowances there are two-thirds of pay, so ₹10,000 of them is added back and the Code's wage figure becomes ₹30,000. That last step is my arithmetic, not the report's. The table runs both PF choices on that salary, employer share inside the CTC, as the report's own take-home figure implies.

Dimension Ceiling vs full wages What it means for you
๐Ÿ’ฐ Take-home Ceiling ₹56,400 a month
Full wages ₹52,800 a month
⚠️ Full-wage PF costs ₹43,200 a year in hand
๐Ÿงพ PF wage ceiling Ceiling 12% of ₹15,000
Full wages 12% of ₹30,000
⚠️ Every rupee above the cap is a choice
๐Ÿ”’ Locked savings Ceiling ₹3,600 a month
Full wages ₹7,200 a month
✅ Retirement money builds twice as fast
๐Ÿ“Š Gratuity base Ceiling ₹30,000 in wages
Full wages ₹30,000 in wages
✅ Exit payout rises whichever PF you pick
⚖️ Legal footing Ceiling Ministry-backed default
Full wages voluntary extra
✅ Grounds to query a full-wage deduction
๐Ÿ Best suited for Ceiling rent or an EMI due monthly
Full wages money you won't touch for years
๐Ÿ Choose by when you need the cash

The monthly gap does not vanish; it moves into a locked account, and half of it is your employer's share. Whether that counts as a loss depends on your rent and EMIs, not on the law. What the law settles is that you should be asked. Gratuity rises either way: it follows the Code's wage figure, not your PF election.

₹30,000. Code wages. Half of CTC line. Basic and DA: ₹20,000. Added back: ₹10,000. Allowances kept out: ₹30,000. Monthly CTC: ₹60,000.

If your allowances add up to more than half of your CTC, the slice above that half now counts as wages, so work out that one number before you read any revision letter. Derived by applying the Section 2(y) add-back to OutlookMoney's ₹60,000 worked example.

Is 50% basic salary mandatory under the new wage code?

No, the Code on Wages does not require basic pay to be exactly half of CTC; it requires excluded allowances above half of total remuneration to be counted as wages, whatever the payslip calls them.

KS&K makes the point directly: the rule does not oblige an employer to designate exactly half of CTC as basic. So when a revision letter says the law forced basic up, it overstates the law. That is worth raising, because a higher printed basic can drag PF up with it while the add-back alone would not.

The ceiling itself is not moving soon. People Matters reported on 3 December 2025 that the government made no commitment to raise the EPF wage ceiling to ₹30,000, saying any change needs extensive stakeholder consultation. Money pushed into PF is also harder to take out than it looks, as the EPF withdrawal rules and the 25% balance lock show. The grey area, and this is opinion, is whether firms that booked a gratuity charge quietly recover it through slimmer increments, and the place to watch is the special allowance line, year on year.

  • A revision raising basic and cutting special allowance equally: CTC flat, PF on a bigger base.
  • A PF deduction worked on a figure above the ceiling, with no written option offered to you.
  • An exit settlement that computes gratuity on the old basic alone, ignoring the added-back slice.

Key Takeaways to act on

  • Your HRA, conveyance, incentives and special allowance together exceed half of your monthly pay.
  • Your PF line divided by 12% gives a number larger than the statutory cap.
  • Nobody has asked you, in writing, whether you want PF above the cap.
  • Your employer disclosed a labour-code charge in its quarterly results.

The decision is narrow: PF at the ceiling or PF on full wages, and the law leaves it open. If two or more of those conditions are true, email payroll this week and ask, in writing, which wage figure your PF uses and whether contribution above the ceiling was your choice. Get the answer before the next revision letter, not after it.

Wednesday, September 30, 2026

Work Phone Reimbursement: What You're Owed

The offer letter says you will use your own mobile for official calls and that no reimbursement is payable. Whether that clause holds depends on where you sit. In California it runs into Labor Code 2802, which requires employers to cover necessary business costs. In India, the sources checked found no equivalent. Work phone reimbursement is a map with blank patches.

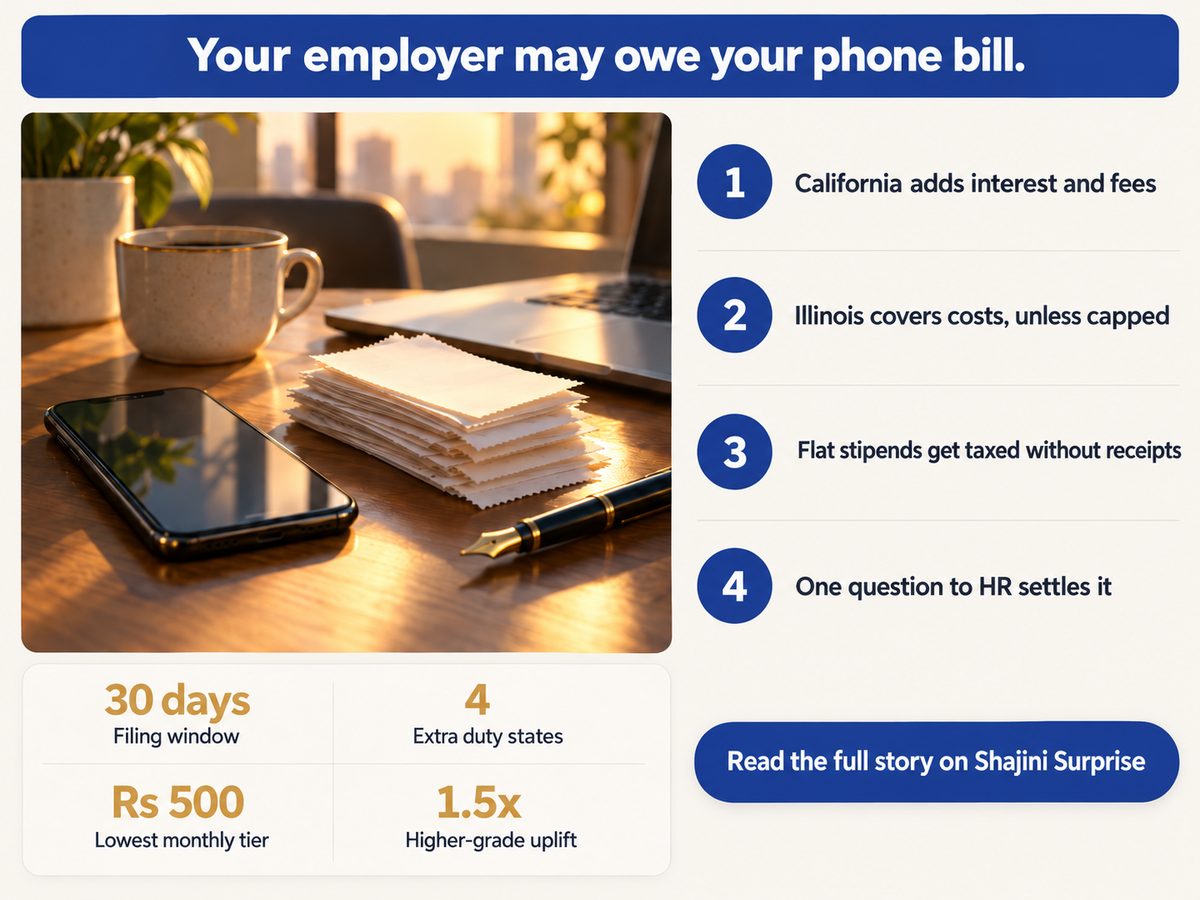
Work phone reimbursement infographic: smartphone and receipts beside four rule points and stats

Your work address, not your employer's headquarters, decides whether your phone bill is owed.

  • California requires a reasonable share of the bill, even on an unlimited plan.
  • Illinois allows necessary costs inside a short window, and a written cap can limit them.
  • In India a fixed BYOD stipend is taxed as salary, while a bill-backed claim is not.
  • No Indian statute turned up in the sources checked, so negotiate in the offer letter.

Does work phone reimbursement depend on your state?

Yes: the United States has no federal statute on this, so your state decides, and California and Illinois, among others, require employers to cover necessary business costs, phones included.

California is the hard case for employers, or at least the costly one. As clockspot's July 2026 state guide summarises the statute, employers owe necessary business expenditures plus interest and attorney's fees, so an unpaid phone bill becomes a fee-shifting claim. Kelley Drye's December 2025 review says the 2014 Cochran v. Schwan's Home Service ruling (as of 2014) requires a reasonable share of the bill whether or not the plan was unlimited. "I would have paid for the plan anyway" is no defence. Sizing that share starts with your bill, as what unused data costs on a bundled recharge shows.

Illinois asks more of the employee. Its wage-payment law, per clockspot, covers necessary expenditures but sets a submission window and lets employers cap the amount in writing. As of 2024, Prokhorov v. IIK Transport holds that refusing submitted phone and internet costs may violate it, per Kelley Drye. Filed claims are enforceable; ones you never filed probably are not.

Federal law adds one narrow test: the Fair Labor Standards Act only bars unreimbursed costs that push pay below the minimum wage or overtime floor, so a well-paid employee has no federal claim. Montana, North Dakota, South Dakota and New Hampshire carry broad duties; New York and Pennsylvania apply only where the employer promised.

The clause sits beside terms like pro-rata gratuity for fixed-term IT staff. Four figures, from Kelley Drye, clockspot and Pluxee, decide the rest: filing time, broad-duty states, allowance size and grade uplift.

Illinois Claim Window

30 days

Late bills can be refused

Other Broad-Duty States

4 states

Your desk decides, not HQ

Lowest Flat Allowance

Rs 500 a month

Taxed without bills attached

Higher Tier Multiple

1.5x

Half again for higher grades

The window is the figure that catches people. Bills arrive monthly, so a skipped bill can be unclaimable by the time you ask. File every month.

"

The paper decides both fights: a late bill can be refused in Illinois, and an unbilled stipend is taxed in India.

Is a BYOD stipend taxable in India?

Yes: a fixed BYOD stipend is taxed as salary, while reimbursement against bills is not, in either tax regime, according to a March 2026 Pluxee benefits guide.

The guide cites Rule 3(7)(ix) for the tax-free route, a numbering that predates the Income-tax Act 2025, so confirm the current section with payroll. The same monthly sum is tax-free with bills attached and taxed without them, so the paperwork is the whole difference. Its examples come from one vendor's clients, so read them as illustrations, not a market rate.

Whether an Indian employer can make you fund work calls with no payment at all is unresolved in what I found. My view, and only a view, is that such a clause is a price to negotiate, not a rule to obey.

Dimension Bill-backed vs Flat What it means for you
⚖️ Tax rule Bill-backed Non-taxable, both regimes
Flat Taxed as salary
❌ Part of each flat rupee goes to tax
๐Ÿงพ Proof kept Bill-backed One bill, monthly
Flat None asked
⚠️ Skip the bill, lose the tax relief
๐Ÿ’ฐ Low flat tier Bill-backed The actual bill
Flat Rs 6,000 a year
⚠️ Bills above this come from your pocket
๐Ÿ’ฐ High flat tier Bill-backed The actual bill
Flat Rs 9,000 a year
⚠️ Your grade sets the tier, not your bill
๐Ÿ“Š Yearly gap Bill-backed Follows your calls
Flat Rs 3,000 between tiers
⚠️ Ask for the higher tier in writing
๐Ÿ Best suited for Bill-backed Heavy callers who keep bills
Flat Light users, no paperwork
๐Ÿ Decide by how often you call

Paper turns a taxed allowance into a tax-free one. The yearly figures are my arithmetic, twelve months of each tier. The map below covers whether you have a right at all.

California. Broad duty. Share of the bill owed. Plus interest and fees. Illinois. Conditional duty. File inside the window. Written caps allowed. US federal. No duty. Pay-floor cases only. Well paid, no claim. India. None found. No statute in sources. Bills keep it tax-free.

In a duty state such as California or Illinois your phone bill is a claim you can file; elsewhere it is a negotiation to win in the offer letter. India's tile means none found in the sources checked, not none exists.

What can go wrong with a phone claim?

A claim is easiest to lose on paperwork, not principle: a late filing, a missing bill, a cap you signed without reading, or an exit where unpaid amounts never reach the final settlement.

The exit is where unclaimed costs disappear. India's 48-hour full and final settlement deadline now carries penalties, so list every pending phone claim in writing before your last day.

The usual advice is to take whatever stipend is offered because it is simpler. It is simpler for the employer. Take the flat sum only if you would never keep a bill.

  • A written cap can lower the amount, so read the policy first.
  • A chat promise is weak where the state applies only if the employer promised.
  • A stipend with no bills is taxed, so take-home lands below the headline.

Key Takeaways to act on: tick any that describe you.

  • Your desk is in a broad-duty state, whatever the head office says.
  • Your payslip shows a fixed phone line and nobody asked for a bill.
  • Your offer letter is silent on phone costs, or the promise was verbal.
  • A cap sits in the policy and you have not reread it.

This week, put your offer letter and latest payslip side by side and email HR one question: is the phone line bill-backed reimbursement or a flat allowance? Then decide: if you call for work often, keep the bills and claim monthly; take the flat sum only if you never will.

Monday, September 14, 2026

New Gratuity Rules 2026: One Year Counts

The clause runs to one sentence. Where an employee completes one year of continuous service, gratuity shall be applicable on a proportionate basis. That is the whole of it, published by the Press Information Bureau in its Code on Social Security factsheet on 22 November 2025, a day after the four labour codes took effect. And the new gratuity rules 2026 inherited from that line have already changed what a fixed-term contract at an Indian IT services firm is worth on the way out. Nobody sent you an email about it. Your offer letter still says five years, because your offer letter was written before the codes existed.

Timeline graphic explaining the new gratuity rules 2026 for fixed-term Indian IT employees

Key Takeaways

If you are on a fixed-term contract, gratuity now starts accruing at one year instead of five, and it is paid pro rata.

  • Permanent employees are untouched: the five-year continuous-service rule still governs them.
  • The entitlement runs from 21 November 2025 forward, not backward over service you have already given.
  • Part-years above six months count as full years, so your exit month can change the payout.
  • Your appointment letter and payslips are the only proof of continuous service you control. Keep them.

Why The New Gratuity Rules 2026 Cut Two Ways

The one-year entitlement applies to fixed-term employees only, so the same reform that hands a contract worker a real exit payment also gives employers a reason to think harder about who gets a fixed-term paper and who gets a permanent one.

Here is the part the coverage keeps missing. A fixed-term employee at month thirteen now has a statutory claim that a permanent colleague at month thirteen does not. That is not a drafting accident. Fixed-term hiring in Indian IT grew precisely because it carried no tail: no gratuity, no retrenchment friction, no long service liability. The Code on Social Security took the cheapest part of that arrangement away. What it did not do was make fixed-term work safer. It made it costlier, and cost gets managed.

The bills arrived fast. Forbes India reported in January 2026 that TCS booked a statutory charge of Rs 2,128 crore in the third quarter of FY26, which pulled its profit down 13.9 percent year on year. That is one firm, one quarter, one set of provisions being trued up. Read that alongside the EPF withdrawal lock that now delays how much of your corpus you can actually take and a pattern shows up: your statutory entitlements are growing on paper while the time and conditions attached to reaching them are growing too.

New eligibility

1 year

Fixed-term staff, pro rata

Accrual rate

15/26

Days of wages per year served

Payment window

30 days

Interest accrues after that

Q3 FY26 charge

Rs 5,000 cr

Six IT majors, one quarter

Those four numbers describe the same reform from two ends. Two of them are what you can claim, one is how fast the money has to reach you, and the last is what the industry booked when its accountants finally priced the first three. Fisher Phillips, writing for employers in March 2026, put the payment obligation plainly: calculate, notify, pay, and carry interest if you miss. That is a harder deadline than most exit processes in this industry currently hold to, and it sits right next to India's 48-hour full and final settlement deadline, which covers the rest of your dues.

"

Your contract type, not your performance, now decides whether you leave with a gratuity cheque or a handshake. That is the whole reform, and it was never designed to be neutral.

Do Permanent Employees Still Need Five Years?

Yes, the five-year continuous-service requirement survives intact for permanent employees, payable on termination, superannuation, resignation, death or disablement, and only fixed-term staff got the one-year door, on a strictly proportionate basis.

A lot of the commentary in November treated this as gratuity being cut to one year for everyone. It was not. If you are a permanent employee four years and eight months into your job, nothing about your position changed on 21 November 2025, and anyone telling you otherwise has read a headline and not the clause. What did change sits in the table below, and most of it changes the arithmetic rather than the eligibility.

CategoryDetailInsight
Start date21 November 2025, applied prospectivelyService given earlier does not count
EligibilityFixed-term at one year, permanent at fiveContract type now sets the wait
Wage baseBasic must be at least 50% of total payRaises the base gratuity multiplies
RetrenchmentApproval threshold moved from 100 to 300 workersEasier to cut you before you vest
Part yearsA part-year above six months counts as fullThis is where the doubling happens
Our readingMonth 19 credits two years, month 18 credits oneDerived here, not a published figure
Best suited forFixed-term staff with a renewal date in handTime the exit, do not improvise it

Two rows there deserve a second look together. The wage-base change raises the number your gratuity multiplies against, and the retrenchment change makes it administratively easier to end your employment before the multiplication ever happens. Both are in the same reform package. Whether that nets out in your favour depends entirely on how long you stay, which brings us to the only calculation in this piece that actually matters.

How Is Pro-Rata Gratuity Calculated For A Fixed-Term Employee?

You take the last drawn wage, multiply by fifteen twenty-sixths, and multiply again by years of service, where any completed year counts and a leftover period above six months counts as a whole additional year in its own right.

That last clause is where the money hides, and almost nobody plans around it. Work it through. A fixed-term employee who exits at eighteen months has one completed year plus exactly six months, and six months is not more than six months, so one year is credited. The same employee who stays into month nineteen has one completed year plus a part-year that clears the threshold, so two years are credited. Same contract, same salary, one extra month of work, and the entitlement doubles. That is our own reading of how the completed-year and part-year rules interact rather than a figure any of these sources prints, and it is worth checking against your own appointment terms before you sign anything on the way out.

21 Nov 2025. Month 12. Month 18. Month 19. Exit. Codes in force. Claim opens. One year credited. Two years credited. Payment window opens.

Reading the timeline in plain words: the clock starts when the codes came into force, a fixed-term claim becomes possible at the twelve-month mark, the credited service stays at one year right through month eighteen, and it steps up to two years once month nineteen is reached. The payment window only opens at exit.

Where This Goes Wrong For You

The failure mode is almost never an employer refusing to pay, it is a broken service record, a contract quietly reclassified, or an exit timed three weeks too early, and all three happen during an ordinary notice period.

Continuous service is the load-bearing phrase in the whole clause, and it is also the one most easily damaged. A gap between two fixed-term renewals, a transfer between group entities, a short stint parked on a vendor payroll: each of these can reset the count, and each of them is presented to you as an administrative formality. I would push back on that framing, though I understand why people accept it. The paperwork usually arrives with a raise attached.

Watch for these:

  • A renewal that starts a few days after the previous term ended, rather than the day after.
  • A new appointment letter that changes the employing entity while your desk, manager and project stay the same.
  • A relieving letter that omits the start date, or gives a start date that does not match your first payslip.
  • An exit date proposed by your manager that lands just short of a month boundary you have been counting toward.
  • A settlement statement that lists gratuity as nil without stating which rule it applied.

If your contract says fixed-term: count your months from the start date on your first appointment letter, not from when the codes took effect, then check which side of the part-year threshold your planned exit falls on.

If your contract says permanent: nothing here changes your eligibility, but the wage-base rule may quietly change what your eventual payout multiplies against, so read your revised salary structure rather than your net credit.

If you cannot tell which you are: that is itself the finding. Ask HR in writing which classification your service is recorded under, and keep the reply.

Does Resigning Before Five Years Mean No Gratuity At All?

For a permanent employee, yes, resignation before five years of continuous service still leaves you with nothing on this head. For a fixed-term employee past the one-year mark, no, the proportionate entitlement survives resignation.

This is the sharpest split the reform created, and it deserves more attention than it is getting. The same resignation letter produces two completely different financial outcomes depending on a classification most employees never chose and many cannot name. If you are watching the silent layoff signals most tech workers miss and thinking about jumping first, the classification question comes before the timing question. And if your reason for leaving is the commute and the anxiety that came with forced return to office, it still comes first, because the answer can be worth a month of pay.

This week, pull out your appointment letter and your most recent payslip, and confirm three things in writing with HR: your recorded classification, your recorded date of continuous service, and the rule under which your gratuity will be computed at exit. Do it now, while you are not negotiating anything. The answers are much harder to get once you have resigned.

Related: how the 50% wage rule changes your take-home pay and gratuity base

Monday, September 7, 2026

Who Pays For A Work Phone: BYOD Reimbursement Explained

Who pays for a work phone is a question most Indian employees never actually ask, because the answer arrived by default the day someone in HR said "just use your personal number for now" and nobody ever revisited it. Some companies hand you a device. Most just expect the calls to happen, on your SIM, on your bill, indefinitely.

Employee checking a personal phone bill to see who pays for a work phone

There is no single Indian law forcing an employer to reimburse a personal phone used for work. It runs on company policy and your own contract, which means three very different outcomes are all equally common.

  • Company-issued device: the employer owns the SIM, the handset, and the bill.
  • A fixed monthly allowance: paid whether you used Rs 200 or Rs 2,000 of it.
  • Bring your own, no reimbursement: the default in most small and mid-size Indian offices.

Who Pays For A Work Phone, By Policy?

Whoever your employment contract or HR policy names, since Indian labour law sets no general floor for phone reimbursement the way it does for statutory bonuses or provident fund contributions.

That absence matters more than it sounds. It means the decision genuinely comes down to what was negotiated, written down, or simply assumed at your specific company, and assumed is doing a lot of work in that sentence. A field sales role that lives on the phone gets an allowance almost everywhere, because the cost of not paying it shows up quickly in missed calls and slower response times that management notices. A desk role that takes the occasional work call rarely does, even though the phone, the data plan and the wear on the handset are all still real costs landing on one person's account, spread quietly across twelve monthly bills that nobody in HR ever sees added up. Chasing that gap once it is in dispute feels a lot like fighting an automated support loop that was never designed to hear your specific case.

Statutory Phone Mandate

None

Runs on contract, not law

Voice-Only Yearly Cost

Rs 1,849

Airtel, calls and SMS only

Bundled Yearly Cost

Rs 3,599

2GB a day added on top

Gap An Allowance Could Cover

Rs 1,750

A year, on the numbers alone

"

No regulator is coming to settle who pays for a work phone. The number only moves once someone in your specific office writes it down.

The Three Ways Companies Actually Handle It

A company-issued device is the cleanest option on paper, since the employer owns the SIM, sets the plan and carries every rupee of the bill without touching your personal number at all.

A fixed monthly allowance is the middle ground, paid on top of salary regardless of what you actually spend that month, which works well for a role with predictable call volume and badly for one that spikes around a deadline or a client emergency. Bring-your-own-device with no reimbursement is the quiet default almost everywhere else, and it survives mostly because nobody totals up the real annual cost the way operators had to total up the fraud risk before the KYC display-name rules landed. Written down and added up over a year, a personal number carrying work calls is not a favour. It is an unpaid subscription, renewed automatically every recharge cycle without anyone signing off on the price. Ask three colleagues at three different companies which of these three arrangements they are actually in, and do not be surprised if none of them can answer immediately, because most people have never had to add the number up.

ArrangementWho PaysBest Suited For
Company-issued deviceEmployer, 100% of the billClient-facing or heavy call-volume roles
Fixed monthly allowanceSplit, one flat sum paid all 12 months regardless of usePredictable, moderate call volume
Actual-bill reimbursementEmployer, against submitted receiptsIrregular usage spread across 12 months
Bring your own, unpaidYou, in full, every yearNobody, honestly, but very common
Second SIM, voice-onlyRs 1,849 a year if self-fundedCalls and OTPs only, no work apps

Notice where a second SIM sits in that table. It is the cheapest fix available to you personally, and it does not require your employer to agree to anything at all.

When A Second, Voice-Only Line Makes Sense

A voice-only second SIM makes sense the moment work calls are the entire requirement, since a role that never needs the work number to run an app or browse on the move has no reason to pay for a bundled data pack.

Airtel's voice and SMS voucher runs Rs 1,849 a year against Rs 3,599 for the equivalent bundled pack with 2GB of daily data, a gap of roughly Rs 1,750 on a line that would only ever take calls and forward the occasional OTP. Carry that second SIM in a basic handset or a dual-SIM slot, ask your employer to fund that specific line if a policy exists, and keep your primary personal number entirely out of the arrangement. That separation matters beyond the money: a work number on its own SIM can be handed back cleanly when you leave a job, while a personal number that quietly became the office contact line cannot be un-shared from years of client address books. If a policy does not exist yet, a concrete number like this, rather than a vague request for "phone reimbursement," is exactly the kind of specific ask that gets a policy written, the way a hard deadline changed behaviour where a soft guideline never did.

What A Voice-Only Line Will Not Fix

A voice-only second SIM does not help if your actual job needs the work number to run apps, receive attachments or stay reachable on chat, since none of that functions without a data connection of some kind.

It also does not resolve who owns the number if you leave the company, or what happens to years of client contacts saved against a line you paid for yourself. Ask what happens to the SIM, the number and every client who saved it, before you agree to anything. Put both questions to HR before you commit to any arrangement, personal SIM or company-issued, because a policy that only half answers the question tends to behave the way a rule that promises the whole amount while quietly holding a quarter back usually does.

Key Takeaways

  • No Indian law forces reimbursement for a personal phone used at work; it runs entirely on your contract or HR policy.
  • Company device, fixed allowance and unpaid bring-your-own are the three arrangements you will actually meet.
  • A voice-only second SIM costs about Rs 1,750 less a year than a bundled data plan, if the job only needs calls.
  • Settle who owns the number and the saved contacts before you agree to any arrangement, not after you leave.

So this week, work out which of the three arrangements you are actually in, put the real annual number in front of whoever sets policy, and if the job genuinely needs only calls and SMS, ask for that specific voice-only line rather than a vague monthly top-up. The gap between what a work phone should cost and what most people quietly absorb is bigger than a single recharge screen ever makes it look.

Related: work phone reimbursement

Saturday, August 22, 2026

PF Withdrawal Rules 2026: Why 100 Percent Actually Means 75

The email lands on a Friday. Your role is redundant, your last working day is the thirty-first, and HR attaches a settlement sheet you will read four times without really reading it. Somewhere in that afternoon you open the EPFO portal. Years of contributions sitting there, yours, and every headline you have seen this summer says you can now withdraw the whole thing.

You can't. Not the whole thing, and not soon.

PF Withdrawal Rules 2026: Why 100 Percent Actually Means 75

TL;DR: The EPF Scheme 2026 does let you claim 100% of your eligible balance. But a quarter of the account is earmarked and stays put, so the real ceiling is 75%. And the wait for a full premature settlement after leaving a job moved from two months to twelve.

Why The Withdrawal Headline Got It Backwards

The coverage was not wrong. It was incomplete in exactly the place that decides whether you make rent. "Withdraw up to 100%" is a real phrase from a real government release, and it refers to 100% of the eligible balance. Eligible balance is what remains after the scheme earmarks 25% of your contributions as a minimum balance you cannot touch while the account stays open. Do that subtraction and the number on the screen stops being a hundred and becomes seventy-five.

And the framing matters more than usual here, because the people who most need the money are the ones reading fastest. Anyone who has just been through a restructuring knows the mental state. You are scanning for a number, not for a qualifier. If you budgeted your notice period around the full balance and the portal releases three quarters of it, that gap is not an accounting curiosity. It's a month of expenses.

Then there's the part almost nobody led with. The Ministry of Labour and Employment's 13 October 2025 release put the waiting period for a premature final settlement at twelve months, up from two. Read that against what actually happens when a job ends in India. The 48-hour full and final settlement deadline now forces your employer to clear dues fast, which is genuine progress, but employer dues and your own provident fund are two different taps. One got faster. The other got a ten-month longer queue. If your exit was one of the quiet layoff patterns most people miss, where the paperwork says resignation and the reality says otherwise, you are in that queue with no severance argument to make.

Wait for full premature settlement

12 months

Previously two months

Auto-settled claim ceiling

Rs 5 lakh

Cleared without documents

EPFO corpus under management

Rs 28 lakh crore

Members' money, not government money

Interest on the retained balance

8.25%

Compounded while locked

The auto-settlement ceiling is the one worth sitting with, because it is doing quiet work. A claim under that limit clears without a human reading your file and without you uploading anything, which is why settlement times have collapsed for ordinary members. Above it, you re-enter the old world of verification, queries and a regional office. Most salaried members with a decade of service will cross that line at some point, and nothing in the new scheme changes what happens on the other side of it.

"

Two months became twelve. For anyone out of work, that single line decides whether the provident fund is an emergency cushion or a retirement statement they can only look at.

What The EPF Scheme 2026 Actually Changed

Strip the announcements down to what a member experiences at the portal and the changes sort into seven items. Some of them are real improvements. Two of them are the ones you will feel.

Category Detail Insight
Minimum balance 25% of the eligible balance is earmarked and stays in the account A quarter never leaves the account
Real ceiling Three quarters of the account is the true maximum you can pull Hundred percent means three quarters
In force from The EPF Scheme, 2026 took effect on 29 June 2026 Already live, not a future proposal
Pension exit The EPS withdrawal benefit now carries a 36-month wait Three years before pension money moves
Categories Housing, essential needs, and special circumstances replace the old list Thirteen old provisions folded into three
No-reason route Twice a year under special circumstances, no justification required Two free passes, no questions asked
Confirmed in A Lok Sabha reply on 10 August 2026 restated the new waiting periods Stated on the floor this month

Read as a whole, the scheme is a trade. Speed and simplicity on the way in, friction on the way out. Thirteen fiddly provisions collapsing into three plain categories is a genuine win, and the twice-yearly no-questions route is more flexibility than members have ever had for a small emergency. The bill for all of that is paid by the person whose emergency is not small.

Your EPF account under the new scheme   75% you can actually reach  ·  Locked

The bar is drawn to scale: the shorter block on the right is the portion of your own account that stays where it is, no matter which category you claim under.

Where This Quietly Costs You

Policy arguments for the lock are easy to make, and some of them are good. Provident fund balances in India get emptied at the first job change and rebuilt from zero, which is how people reach fifty with a corpus that looks like it belongs to a thirty-year-old. Forcing a floor under the account interrupts that habit. Fine. I agree with the goal.

Whether it works is a different question, and this is where I think the confident takes on both sides are running ahead of the evidence. Nobody has published the counterfactual: how many members, blocked from their own savings during a bad stretch, ended up on a personal loan or a credit card at rates no provident fund has ever paid. I have a hunch about which way that number falls. I don't have the data, and honestly, neither does anyone arguing the opposite. Treat anyone who sounds certain about it as someone with a position rather than a finding.

What is not in doubt is who absorbs the friction. Someone with a working spouse and six months of runway will barely notice a twelve-month wait. Someone laid off from a single-income household, already stretched by the commute and the health costs that come with it, notices immediately. Add the tax load salaried employees already carry and the picture gets clearer. The people with the least cushion are the ones the waiting period lands on hardest.

Things worth checking before you plan around any of this:

  • Your eligible balance on the portal is not your account balance. Look for the earmarked portion before you commit to a number.
  • A partial withdrawal under one of the three categories is a faster route than waiting out a premature final settlement, and most people asking for a final settlement do not actually need one.
  • If your claim crosses the auto-settlement ceiling, expect the older, slower verification path and plan your timeline around that, not around the headline turnaround.
  • The pension component moves on its own clock and it is a much longer one. Do not blend the two in your head.
  • Keep your KYC and exit date correct at the employer's end. Almost every rejected claim traces back to a mismatch there, not to the new rules.
10x  Education claims   ·  5x  Marriage claims   ·  1 year  Service to qualify 

Those three limits are the flexibility the scheme did buy you, and they are worth knowing before you assume the only door is a final settlement.

So do the arithmetic yourself before you plan around a number a headline gave you. Log in, find the earmarked portion, subtract it, and build your exit budget on what is left. Then pick a partial withdrawal category instead of a final settlement, because for most people leaving a job this year, that is the difference between money in October and money next August.