Tuesday, November 17, 2026

Overtime Pay for IT Employees: Who Gets 2x

The Code on Wages, 2019, section 14 sets overtime at “not less than twice the normal rate of wages.” It never says when overtime begins, and for overtime pay for IT employees that silence decides the claim: your State fixes the normal day, and your offer letter may already have spent the extra hours inside your base salary. The employer pays double only when both questions go your way.
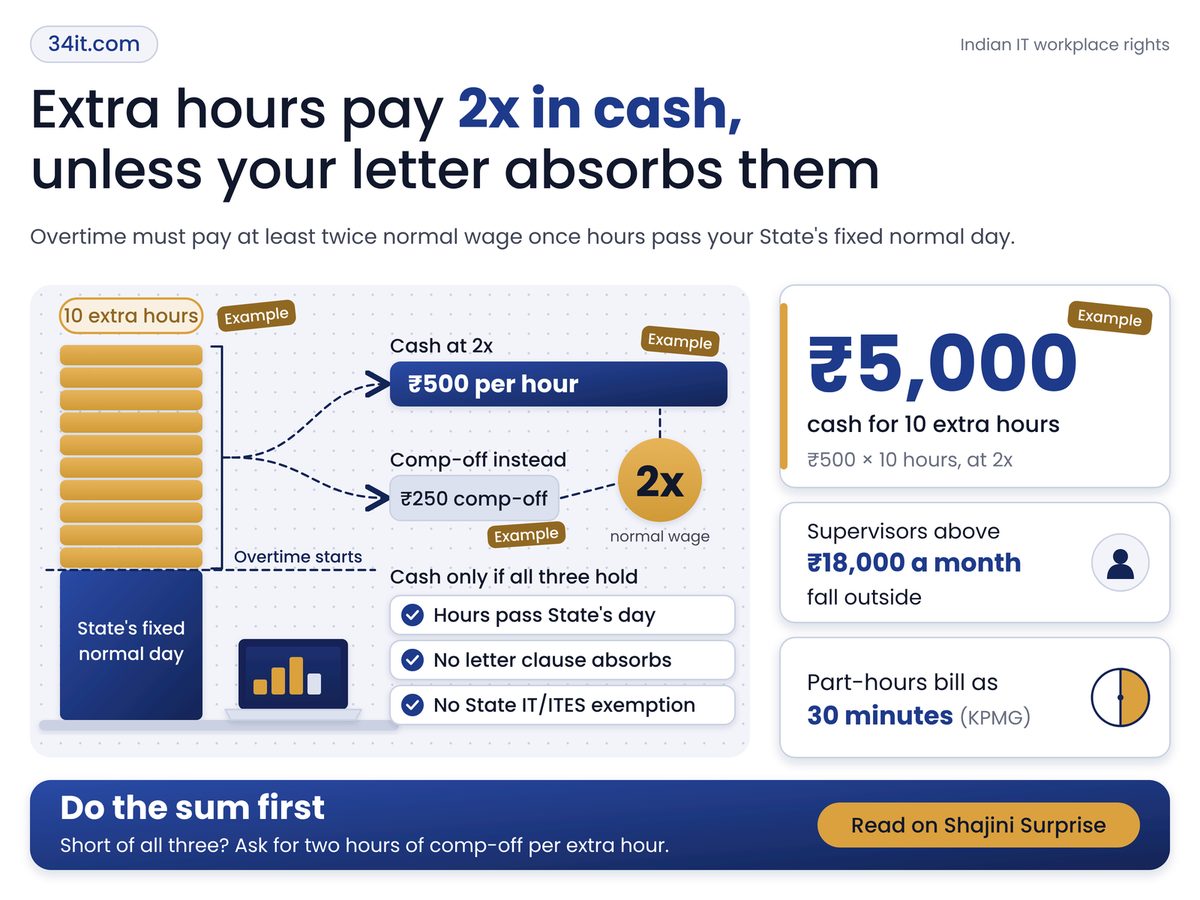
Overtime pay for IT employees shown as ten extra hours above a normal day, paying 2x cash or comp-off

Double pay is in the Code, but you claim it only when every test below holds.

  • The Code sets the multiple at 2x; your State fixes the normal working day.
  • Claim 2x only when all hold: hours past the State-fixed day; no letter clause absorbing them; no State IT/ITES exemption. Otherwise log hours and ask for comp-off.
  • Your hourly rate is monthly wages over contracted monthly hours; the Code never defines “normal rate of wages”.

Is overtime pay for IT employees really double?

Yes, on paper: both the Code on Wages and the OSH Code set overtime at twice the normal wage rate. But each leaves the trigger, the hours beyond which the double rate starts, to the government.

Section 14 covers an employee “whose minimum rate of wages has been fixed” by the hour, the day or a longer prescribed period. It pays “for every hour or for part of an hour” beyond a normal working day. Section 13 lets the appropriate Government fix that day’s length, and the Code names no figure. So “extra” starts where your State says. Not where your day starts to feel long.

The OSH Code’s section 27, in force since 21 November 2025 per India Briefing, pays “twice the rate of wages” for work beyond the hours the government prescribes, counted daily or weekly, “whichever is more favourable to such worker”. A proviso requires the worker’s consent, so extra hours are asked for, not assumed. Our note on leave encashment under OSH Code section 32 covers your leave balance.

Two Codes, one multiple, different reach. The OSH Code’s section 2(1)(zzl) excludes anyone “employed mainly in a managerial or administrative capacity”, and supervisors above a notified pay ceiling. Our reading: a team lead who mostly assigns work is likely outside; an engineer doing “technical” work is likelier inside.

Four numbers decide most claims. Two sit in the Codes and two come from KPMG’s summary of the Central Rules notified on 8 May 2026.

Minimum Overtime Multiple

2x

On every qualifying extra hour

Part-Hour Rounding

30 minutes

A 20-minute stretch bills as this

Quarterly Overtime Cap

144 hours

Central figure, States may differ

Supervisor Pay Ceiling

₹18,000

Supervisors above it fall outside

Divisor and wage base set your hourly rate. KPMG reports a monthly-paid worker’s daily wage as one twenty-sixth of the month, the hour an eighth of that. A 30-day calendar divisor cuts the rate by about 13%, our arithmetic. Which pay counts is the other lever: the 50% wage rule shows how basic pay can shrink.

“

The 2x is the only fixed part of this rule. When it starts, and on which pay, is left to your State and your offer letter.

How is overtime calculated in India?

Divide your monthly wages by your contracted working hours in the month, then multiply by two for each qualifying extra hour. The Code names the 2x, but the divisor and the wage base are conventions you can contest.

Section 2(y) defines wages as “all remuneration whether by way of salaries, allowances or otherwise”, counting basic pay and dearness allowance but not house rent or conveyance allowances. “Normal rate of wages” is defined nowhere, odd for a formula. Our view: basic plus dearness allowance is the defensible floor; gross is the opening ask.

Worked example: assume ₹52,000 a month counted as wages, a 26-day month and an 8-hour day, so 208 contracted hours. Hourly rate: ₹52,000 divided by 208 is ₹250. Ten extra hours at 2x: 10 × ₹500 = ₹5,000. Repaid one-for-one in comp-off: 10 × ₹250 = ₹2,500. We call this your Overtime value; the gap is ₹2,500 a month. Every input is an assumption (example).

What are your extra hours worth?Enter the monthly wage you would count and your extra hours past the State-fixed day. The first figure is your Overtime value at the Code's 2x.
Your numbers
Contracted hours a day
Overtime value at 2x₹5,000
Hour-for-hour comp-off worth₹2,500
Share of quarterly cap20.8%
Cash overtime would be ₹5,000 a month against ₹2,500 for hour-for-hour comp-off. The gap is what a one-for-one offer costs you.Sliders need JavaScript. Figures shown are the article's example.2x from Code on Wages s.14 and OSH Code s.27; 8-hour day, 26-day month and 144-hour cap as KPMG reports the Central Rules (May 2026). Floor, not legal advice.

Which row is yours? Find your situation below, then read across for the move and the reason.

If youDo thisBecause
⏱ Past State dayLog hours; claim 2x in writingSection 14 sets the multiple
๐Ÿงพ Base-pay clauseAsk HR which hours it coversLetters can fold extra work into base
๐Ÿ’ฐ Comp-off offerAsk for 2 hours off per hourMatches the 2x in time, not cash
๐Ÿ Not sureLog hours daily, keep proofA dated log backs any later claim

Comp-off is where most disputes land. A commenter on r/developersIndia, in an unpaid-Saturdays thread dated by its post ID to early 2025, wrote that extra work should be “compensated either by paying OT to the people who are working or by providing compensatory off”. One reader’s view, not a statistic.

2× Cash overtime 2 hourly wages 1× Comp-off 1 for 1 1 hourly wage 2× Comp-off 2 for 1 2 hourly wages 0× Absorbed in base 0 extra wages

This graphic settles whether a comp-off offer is a fair swap: an extra hour is worth two hourly wages in cash, one as one-for-one comp-off, and none once your letter absorbs it. Our arithmetic from the 2x floor in section 14; the comparisons are not legal rates.

Where the double rate stops working

Three limits can erase the 2x, and the first is the one most engineers never check: whether the law counts you as a worker at all.

The sharpest limit is judicial. As the Law School Policy Review (18 May 2026) reports, the Supreme Court’s 1968 Hatta ruling denied overtime to workers paid above the statutory minimum, and Surat Municipal Corporation (2024) leaned on it again. The review argues section 14 no longer supports that. Courts have split. Our view: the review is right, but not yet settled.

The quieter limit is your offer letter. On Team Blind in November 2025, one commenter said an offer letter states that extra work is covered by the higher base salary. That is anonymous reader evidence, not our finding. Whether such a clause can cancel a statutory multiple is untested in the sources read here, so ask HR which hours it covers.

  • State relaxations: India Briefing (December 2025) reports several southern States, Telangana among them, relaxed IT/ITES overtime limits, without dates. Read your State’s notification.
  • On-call hours: log them as hours, and see who pays for work phone bills in India.

Check these about your own job before you send a claim

  • Your offer letter says a higher base “covers” extra work.
  • Your title says lead or manager, but your day is mostly hands-on technical work.
  • Your employer cites a State IT exemption but gives no notification number.
  • Your basic pay is a small slice next to your allowances.

Do one thing this week: count last month’s hours past your State’s fixed normal day and enter them in the calculator for your Overtime value. If the count is above zero, your letter has no absorbing clause and your State has no IT/ITES notification, claim cash at 2x in writing. Otherwise ask for two hours of comp-off per extra hour, since one-for-one pays half. The check is your State labour department’s notification plus the extra-work sentence in your letter. The call is wrong for managers, supervisors above the notified ceiling, and anyone the Hatta line catches.

How we checked this

We read the Code on Wages, 2019 and the OSH Code, 2020 on 17 November 2026, plus the Law School Policy Review analysis of 18 May 2026. Central Rules figures come from KPMG’s summary, not the gazette text. The worked example assumes ₹52,000, 26 days and 8 hours. No product was tested hands-on for this article. Last verified: 17 November 2026. Edited by Shajini, reviewed after publication. Spotted something out of date? Tell us and we will correct it.
Wednesday, November 4, 2026

Joining Bonus Clawback: Reclaim the Tax

A joining bonus letter usually carries one clause: leave inside the bond period and the unearned share comes out of your last salary. Employers recover it gross. You were taxed on it the year it landed. That mismatch is the joining bonus clawback problem, and since 24 February 2026 a tribunal order sits on your side.

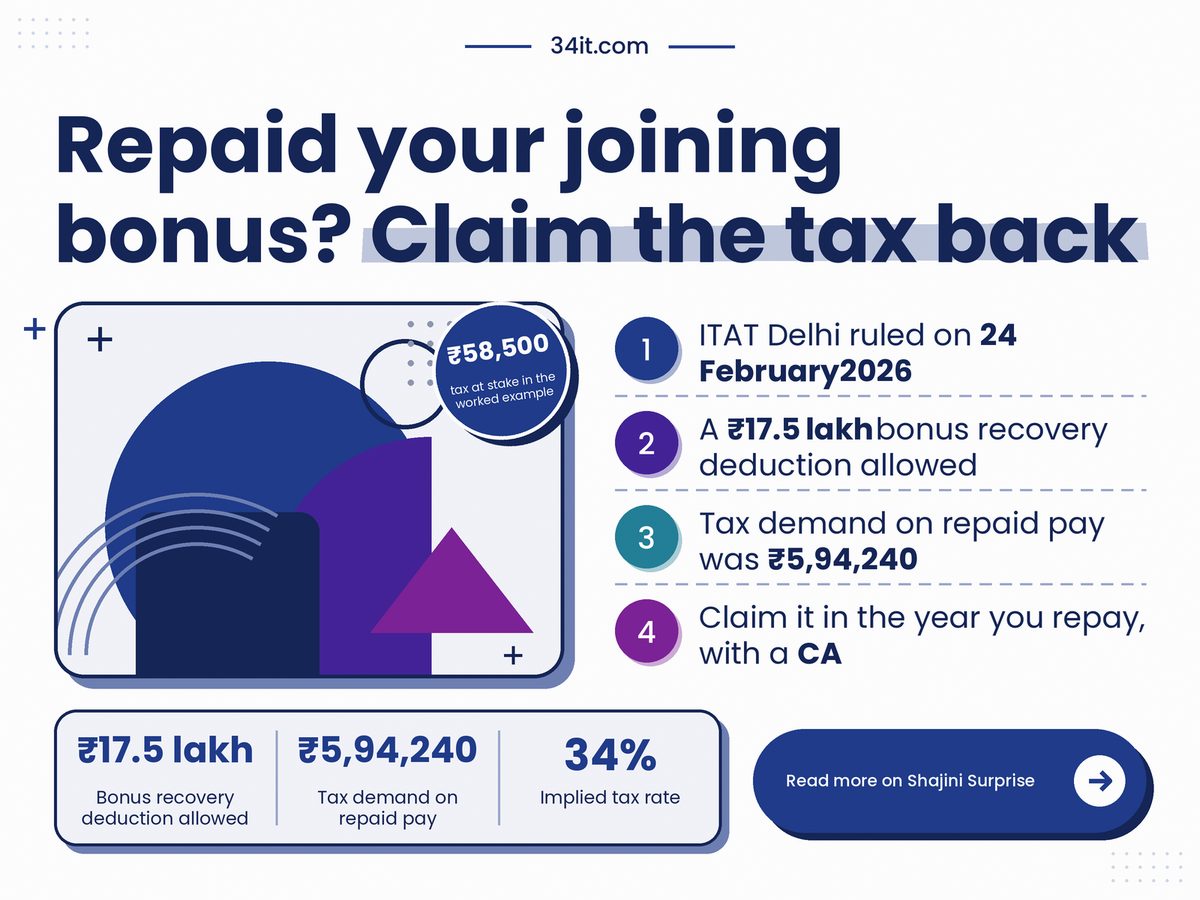
Joining bonus clawback poster: ITAT Delhi allowed a Rs 17.5 lakh recovery deduction against a Rs 5,94,240 tax demand

Yes, claim it in the year you repay: ITAT Delhi treated a repaid bonus as income you never kept.

  • ITAT Delhi (24 February 2026) allowed the deduction in the year of recovery, rejecting the officer's add-back.
  • It is one bench's order: persuasive elsewhere, not binding.
  • Tax at stake is the amount repaid times your slab rate.
  • Challenge any GST on the recovery; Circular 178 puts forfeited salary and bond amounts outside GST.

Can you claim tax back after a joining bonus clawback?

Yes, on one recent tribunal order: ITAT Delhi held on 24 February 2026 that bonus money an employer recovers from your salary is not income you earned, so the deduction is allowed in the year of recovery.

The case is Shriram Bagavathyappan v DCIT (ITA 4815/Del/2025, assessment year 2018-19). A salaried employee was paid a ₹15 lakh joining bonus in 2015-16 and a ₹10 lakh retention bonus in 2016-17, both taxed when paid. He resigned in May 2017. The employer recovered ₹7.5 lakh of the first bonus and all of the second from his 2017-18 salary, and he offered only the salary left over. The officer added the full ₹17.5 lakh back. It stood through the order of 28 June 2021 and the first appeal.

The Tribunal called the add-back an "arbitrary, colourable exercise of power" and said the department should tax income actually earned. It cites no provision granting the deduction, so the logic is clean and the law is thin. ITAT Ahmedabad took the same line in Nandinho Rebello (18 April 2017), taxing only salary received, as our notice period buyout piece explains.

Four numbers show what the fight costs. Three read straight off the order; the fourth is our own division of the demand by the repayment.

Wait for a Verdict

4.7 years

Demand to ruling, our count

Tax Demanded on Repaid Pay

₹5,94,240

Tax on money handed back

Years Between Taxed and Repaid

2 years

Joining bonus taxed, then repaid

Tax Rate Implied by the Demand

34%

Derived: demand divided by repayment

Your slab, not the bonus size, sets what an add-back costs, so multiply what you repaid by your slab for the tax at stake. Whether you owe the repayment at all is a separate fight, covered in the proof problem in an employment bond.

"

Money you handed back was never income you kept. An officer's add-back does not change that arithmetic.

What should you do when your employer recovers the bonus?

Start with three checks: what your Form 16 shows, which year the money went back, and whether the recovery matches your contract. Each points to one action in the table below.

Advice so far has been stricter. A poster on the Blind employee forum wrote in August 2022 that a bonus returned two years later was missing from Form 16, and replies mostly said a later-year repayment cannot reduce income. An undated Moneylife answer found no specific provision for it. These are reader accounts, not statistics, and the 2026 order cuts against them.

If you Do this Because
๐Ÿงพ Gross Form 16 Ask HR for pay net of recovery Tax should fall only on pay you kept
⏱ Repaid later Claim it in the repayment year's return ITAT Delhi, 24 February 2026
๐Ÿ’ฐ GST charged Refuse the 18% line in writing Circular 178 para 7.5: bond amounts
⚖️ Over-recovery Ask for the pro-rata working Contract Act s.74: reasonable sum only
๐Ÿ›  None apply Repay, keep receipts, see a CA The order is persuasive, not binding

How long a repaid bonus stayed taxed

1 FY 2015-17 Bonuses paid and taxed 2 FY 2017-18 ₹17.5 lakh cut from salary 3 28 Jun 2021 Officer adds it back and demands tax 4 24 Feb 2026 Tribunal allows the deduction

Read it to see why the claim belongs to the year you repay: tax on money handed back ran for years before anyone reversed it. Source: ITAT Delhi, 24 February 2026, ITA 4815/Del/2025.

The first two rows hold the money. In the Delhi case the paperwork showed gross pay and the return showed net, and that gap was the whole dispute.

Worked example: assume a ₹3,00,000 joining bonus on a 24-month bond, 9 months served, pro-rata recovery and a 31.2% marginal rate in both years (30% slab plus 4% cess). Unserved share: 24 minus 9 is 15 months of 24, so you repay ₹1,87,500. You were taxed ₹93,600 and kept ₹2,06,400. After repaying, ₹18,900 is left if the tax stays put. Deduct the repayment and tax applies only to ₹1,12,500, leaving ₹77,400. The gap, ₹58,500, is the tax at stake. Try your own bond below; it takes under a minute.

What is your repaid bonus worth back?Set the bonus, your bond and months served, and your tax rate. The bars show the tax at stake and what you keep with and without the deduction.
Your numbers
Recovery basis
Bonus you repay₹1,87,500
Tax at stake₹58,500
Left without relief₹18,900
Left with the deduction₹77,400
The deduction is worth ₹58,500 to you: ₹77,400 left instead of ₹18,900.Sliders need JavaScript. Figures shown are the article's example.Pro-rata by months served is the usual convention; your offer letter decides. Deduction rests on ITAT Delhi, 24 Feb 2026, a persuasive order. Same rate both years. Not tax advice.

Why can a bonus repayment claim still fail?

Because the order binds only the parties to it and names no section granting the deduction, an officer elsewhere can still add the repayment back and leave you to appeal.

The repayment itself can be enforced. In Vijaya Bank v Narnaware (14 May 2025) the Supreme Court upheld ₹2 lakh of liquidated damages under a three-year bond as not disproportionate, so expect to repay and argue about the tax. Recoveries often come out of the full and final settlement, so read yours beside what you are owed, such as leave encashment (or, more precisely, what your policy pays per day).

Then there is the invoice. Paragraph 7.5 of CBIC Circular 178/10/2022-GST (3 August 2022) says amounts recovered on "forfeiture of salary or recovery of bond amount" are not consideration for a service. It does not name joining or retention bonuses; a Tax Management India note of 10 July 2024 applies the same reading to them. Treat that as a strong argument, not a ruling.

  • Check what your employer reported on the income tax portal (Form 26AS or AIS) before filing; if it shows the gross bonus, ask a CA how to present the deduction.
  • Your clause may allow full recovery, not pro-rata. Contract Act s.74 allows only reasonable compensation up to the sum named.
  • In the Delhi case the employer cut the recovery from salary; a cheque repaid after exit differs on its facts.

Check these on your own papers

  • Your Form 16 Part B shows the whole bonus as salary, with no line for the recovery.
  • The money went back in a later year than the one that taxed it.
  • Your offer letter says pro-rata or full, and your months served fit its working.
  • Your exit bill carries a GST, CGST or IGST line on the recovery.

The decision is to claim the deduction in the year you repay, with a chartered accountant, before you file. This week, ask HR for Form 16 net of the recovery and the working behind the amount. This is wrong if you repay in the same year the bonus was taxed, or if the tax at stake is below a CA's fee, so check Form 16 Part B first.

How we checked this

We read the ITAT Delhi order (24 February 2026), paragraph 7.5 of Circular 178/10/2022-GST (3 August 2022), a Tax Management India note (10 July 2024) and an IndiaLaw summary of Vijaya Bank (14 May 2025). The worked example assumes a ₹3,00,000 bonus, a 24-month bond, 9 months served, pro-rata recovery and a 31.2% rate in both years. No product was tested hands-on for this article, and none of this is tax or legal advice. Last verified: 5 November 2026.

Edited by Shajini, reviewed after publication. Spotted something out of date? Tell us and we will correct it.

Friday, October 30, 2026

Notice Period Buyout: Refuse the 18% GST

The clause sits near the end of most Indian IT offer letters: leave before your notice period ends and you pay your salary for the days you skip. That payment is a notice period buyout, and some exit bills now add a second line under it: 18% GST. The tax department said so in August 2022, and two High Courts have since agreed.

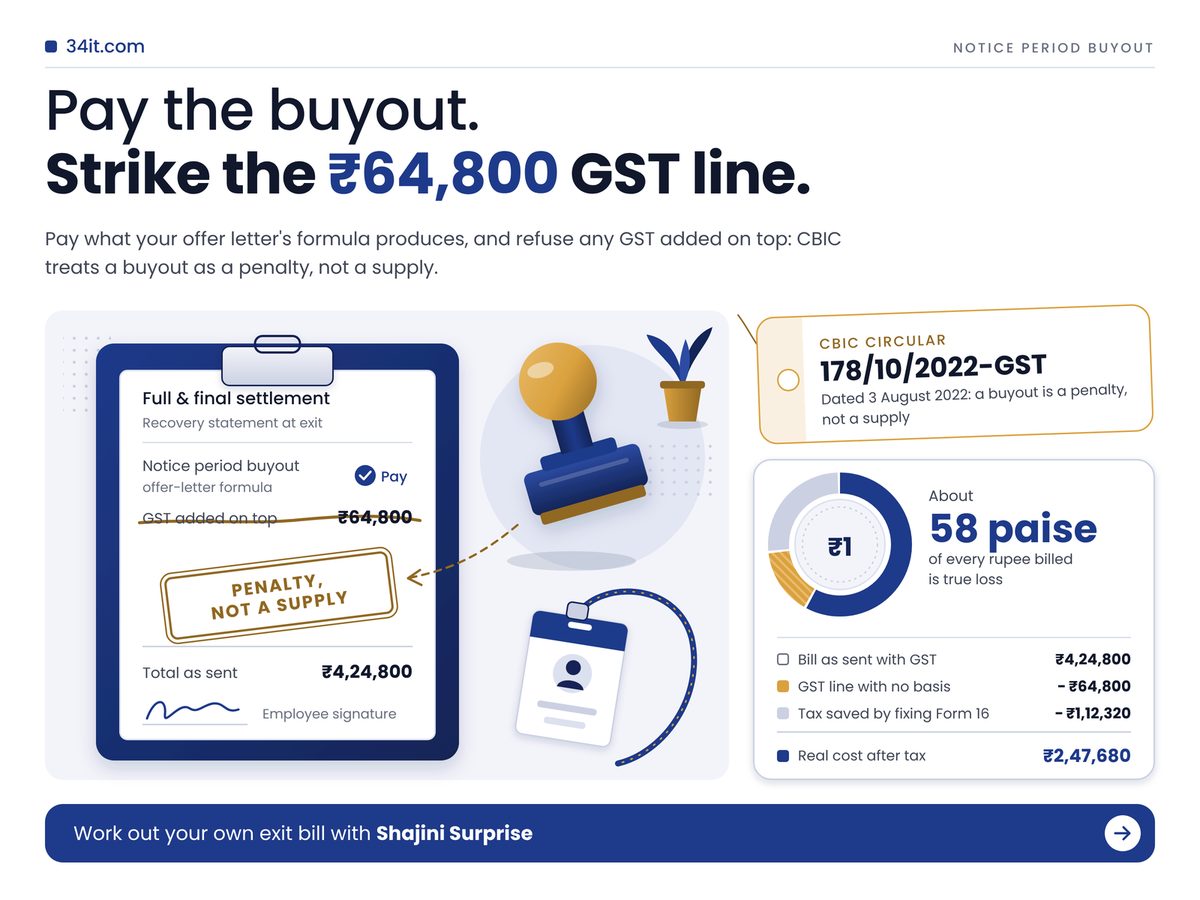
Notice period buyout bill with struck GST line, penalty stamp and rupee gauge

Key Takeaways: Pay your offer letter's buyout formula and refuse any GST added on top.

  • CBIC Circular 178/10/2022-GST (3 August 2022) treats salary forfeited for leaving early as a penalty, not a service, so no GST applies.
  • The Kerala and Gujarat High Courts have treated GST paid on notice pay as refundable.
  • An ITAT Ahmedabad ruling taxes only salary you kept, so the recovery should come off Form 16 income.
  • If your marginal tax rate tops 18%, fixing Form 16 saves more than refusing the GST.

Is GST applicable on notice period buyout?

No, GST does not apply to salary you pay back for skipping notice, because CBIC Circular 178/10/2022-GST treats it as a penalty that buys the employee nothing, so it is not consideration for any supply. Read the circular itself: paragraph 7.5 never says "notice period". It covers "forfeiture of salary" when an employee leaves before the agreed period, adding that the employee "does not get anything in return".

The Kerala High Court read notice pay into that line in Manappuram Finance (2022), as reported by Taxmann, and called the circular clarificatory, so it reaches exits before August 2022 too. The same paragraph covers an employment bond's proof problem.

The 18% line mostly traces to one Gujarat case. Amneal Pharmaceuticals' advance ruling, reported in November 2021, held GST payable. Its appeal split between the two members on 9 February 2022, and under CGST Act s.101(3) a split means no ruling issues. An HR policy citing Amneal cites nothing.

The practice outlived the law. An undated complaint on Medium says an employer "recovered the Notice period shortfall amount with 18% GST".

Four numbers set how hard you can push. They come from the Gujarat High Court's 2025 Aculife Health Care ruling (TaxGuru's report), the Model Standing Orders notified on 8 May 2026 (JSA's reading) and Code on Wages s.18.

Wages Due After Resignation

2 working days

Any netting must fit this

GST One Employer Paid on Notice Pay

₹45.14 lakh

Ruled never tax, refundable

Workers Before Standing Orders Apply

300

Smaller firm: contract alone governs

Cap on Listed Wage Deductions

50%

Of one wage period's pay

The refund card is a warning. Aculife paid the tax itself, and the court held it was never tax, with the two-year refund clock running from 3 August 2022. On that reading, pre-circular claims shut on 3 August 2024 (our arithmetic), so refuse GST at the bill. If your buyout runs on basic pay, see how the Code on Wages add-back reshaped basic pay.

"

The employee does not get anything in return. CBIC wrote that in 2022, and no HR invoice turns it back into a service.

What each line of a buyout bill should say

A correct buyout bill shows one line, the contract formula applied to the days you did not serve after leave set-off, with no GST, and your Form 16 should then show only the salary you kept. In Nandinho Rebello v. DCIT (18 April 2017), ITAT Ahmedabad taxed only the salary actually received after ₹2,76,744 of notice pay was held back, per BCAJ's case note. Your relief is your marginal rate on the recovery; GST is a flat 18%. Above an 18% marginal rate, Form 16 matters more than the GST, and most advice gets that order backwards.

Worked example: assume ₹2,40,000 monthly pay used for the buyout, a 90-day notice period, 30 days served, 15 leave days set off, and a 31.2% marginal rate (30% slab plus 4% cess). Unserved days: 90 minus 30 minus 15 is 45. A day's pay is ₹2,40,000 divided by 30, or ₹8,000, so the buyout is ₹3,60,000. Add 18% GST and the bill reads ₹4,24,800, of which ₹64,800 has no basis. Keeping the recovery out of taxable salary saves ₹1,12,320. Real cost: ₹2,47,680, or ₹1,77,120 below the bill. Try your own pay below; it takes under a minute.

What does your buyout really cost?Set the pay your contract uses, your notice terms and your tax rate. The split shows what you truly lose, the tax you should not pay, and the GST line to refuse.
Your numbers
Buyout under your formula₹3,60,000
GST line to refuse₹64,800
Tax you should not pay₹1,12,320
Real cost after tax₹2,47,680
Your tax line, ₹1,12,320, is bigger than the GST line, ₹64,800: fix Form 16 as well as the bill.Sliders need JavaScript. Figures shown are the article's example.Monthly pay divided by 30, times unserved days: a common offer-letter convention, your contract decides basic or gross. GST should be nil per CBIC Circular 178/10/2022-GST (3 Aug 2022). Not legal advice.

Find the row matching your exit bill and read across.

If you Do this Because
๐Ÿงพ See GST billed Ask HR to delete it in writing Circular 178, para 7.5: not a supply
๐Ÿ’ฐ Quoted flat sum Pay the offer-letter formula only Contract Act s.74 caps it at the named sum
๐Ÿ“Š Form 16 gross Ask for salary net of recovery At the 30% slab, ₹31,200 saved per ₹1 lakh
⚖️ Face F&F netting Consent in writing after checking the sum s.18 lists no buyout deduction
๐Ÿ›  None apply Pay the formula sum, keep the receipt Proof the contract is settled

On the flat-sum row, Indian Contract Act s.74 limits breach compensation to a reasonable amount no higher than the sum the contract names.

Where a GST-loaded buyout bill really goes

58.3% 26.4% 15.3% Real cost of the buyout after tax Income tax you should not pay on it GST added with no legal basis

Of every rupee on a GST-loaded buyout bill, only about 58 paise is a true loss, so win back the other two slices first. Derived from the worked example, with GST nil per Circular 178/10/2022-GST.

Can notice pay be deducted from full and final settlement?

In practice yes, employers net a buyout from your full and final settlement under the contract or your signed consent, though Code on Wages s.18 does not list notice recovery among the deductions it permits from wages. That is the grey area. Our view: netting rests on your contract and consent, not the Code, so ask for it in writing and challenge any figure above the formula. We found no ruling that tests this under the new Code.

Covered establishments must issue a service certificate within 10 days of resignation under the 2026 Model Standing Orders, so holding it over a disputed GST line is their problem. Each leave day set off also cuts the buyout by a day's pay; weigh that against the leave encashment rules (or, more precisely, what your policy pays per day).

  • Rebello is a 2017 tribunal ruling; outside Gujarat it persuades but does not bind your assessing officer.
  • JSA flags state exemptions such as Karnataka's for IT and ITES firms.
  • Pay the undisputed formula amount on time, so only the GST stays open.

Before you pay, check four things

  • Your exit bill shows a line marked GST, CGST, SGST or IGST.
  • Your offer letter names the days and basic or gross.
  • Your Form 16 Part B shows gross salary before the recovery comes off.
  • HR can show certified standing orders that cover your role and state.

The decision is to pay the formula, not the invoice. This week, before signing your F&F, email HR asking them to remove the GST line under Circular 178/10/2022-GST, paragraph 7.5, and to issue Form 16 net of the recovery. This is wrong only if the bill shows no GST and Form 16 is already net, so check Part B first.

How we checked this

We read CBIC's Circular 178/10/2022-GST (3 August 2022) in full, the Gujarat High Court's Aculife ruling (2025) in TaxGuru's report, ITAT Ahmedabad's Rebello order (18 April 2017) in BCAJ's note and JSA's May 2026 note on the Model Standing Orders. The worked example assumes ₹2,40,000 monthly pay, 45 unserved days and a 31.2% marginal rate. No exit bill was audited first-hand, and none of this is legal or tax advice. Last verified: 30 October 2026.

Edited by Shajini, reviewed after publication. Spotted something out of date? Tell us and we will correct it.